
Conventional
Buyers with solid credit- Low down payment options for qualified buyers
- No mortgage insurance with a larger down payment
- Mortgage insurance can be removed as you build equity
Whether you're buying your first home or moving up, Tom matches you with the right loan program and a pre-approval letter that strengthens your offer.
No credit pull to start · Options from 45 lenders · Call or text 603-851-4982

Need an inspector, attorney or mover before closing? Service Connect lists local home pros as they join.
Have your documents ready? Start the secure application with Tom now.
As a mortgage broker, Elite Mortgage Group works with 45 lenders, so Tom can match you with the program that fits.
The loan program matcher points you to the programs worth a closer look for your plans.
Try the loan program matcherConventional, FHA, VA and more in one table, with what each program asks of you.
Compare programs side by sideSelf-employed or investing? See how bank statement and DSCR loans work
Program availability, eligibility and terms vary by lender and are subject to change and to underwriting approval. Not a commitment to lend.
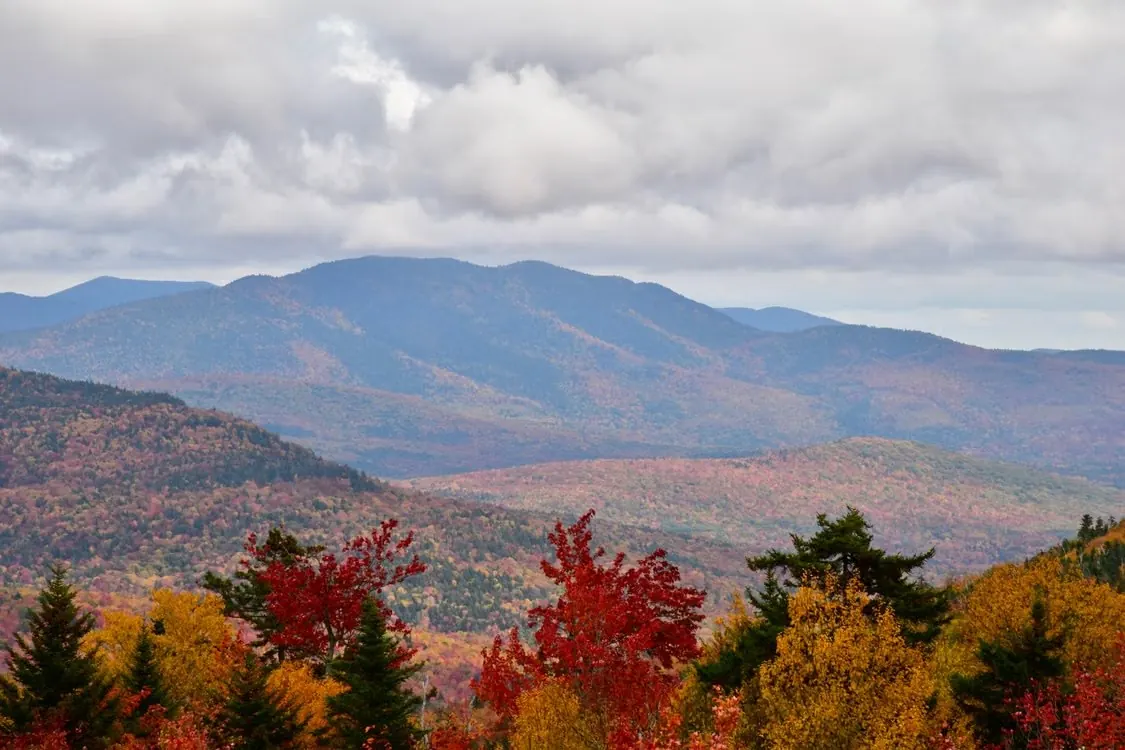
Lakes, mountains and seacoast, all within an easy drive of southern New Hampshire.
Many buyers relocate to southern New Hampshire from Massachusetts for more space and no state income or sales tax.
The trade-off is property tax. NH towns fund most local services this way, with rates quoted per $1,000 of assessed value, so two homes at the same price can carry very different payments. Tom shows you the full monthly cost, town by town, before you fall for a house.
Read the Massachusetts to NH guide
Compare MA and NH taxes with your own numbers
Tom works alongside experienced agents across southern New Hampshire and can introduce you to one who knows the towns and price range you're considering.
Your agent and your loan officer, working as one team.
Agent introductions are free and carry no obligation. Thomas MacDonald and Elite Mortgage Group, LLC neither pay nor receive any fee, referral or other thing of value for introductions.
Coming soon: inspectors, movers and more in Service Connect Own a local business? See the free NH Business HubMany first-time buyers qualify with a low down payment, and NH Housing offers help with upfront costs for eligible buyers. Tom walks you through what fits before you start touring.
Read the first-time buyer guide
Found a home with an FHA or VA loan? Ask whether it's assumable.
Hoping the seller will help with closing costs? See seller credits and rate buydowns.
Getting ready to apply? See credit and your mortgage.
Three brief steps online, then Tom calls to talk through programs and payments. No credit pull to get started.
Don't see yours? Call or text Tom or browse more answers.

Once you're pre-approved, hold off on new credit, large purchases and job changes until after closing, and call me before moving money between accounts. Small changes could affect your approval.
Many letters are good for about 60 to 90 days, depending on the lender, because credit and income documents need to stay current. If yours runs out before you find a home, Tom can refresh it with recent pay stubs and statements.
It depends on whether you could qualify while carrying both homes for a while and how much cash you have for the new purchase. Tom can compare buying first, selling first and making your offer contingent on a sale.
You'll receive a Loan Estimate within three business days. Then the appraisal is ordered and an underwriter reviews your file, which may bring requests for a few more documents before you're clear to close.
Yes. Tom walks you through each step, from your first budget to closing day, and explains the first-time buyer options that could fit.
Many programs allow gift funds from a relative. You'll usually need a signed gift letter and a record of the transfer, so talk with Tom before the money moves. See using gift money for your down payment.
Three easy ways to reach Tom. No cost, no obligation and no credit pull to start.
A few quick questions, then Tom calls you.
Hi, I'm Tom. What can I help you with? Pick a topic for a quick answer, or send me a message and I'll reply myself.
Quick answers are automatic, written from this site's guides. They are general information, not advice or a commitment to lend. Messages go to Tom directly.
Most buyers start with a pre-approval, so you know your price range before you tour and your offer is taken seriously. Tom can walk you through it and answer questions along the way.
How pre-approval worksFirst-time buyer guideBuying in NH
You can start your application online through Elite Mortgage Group's secure portal, or send Tom a message and he'll help you get started. The site itself never asks for your Social Security number or documents.
Start my applicationWhat to have ready
Rates change daily and depend on your credit, the loan type, the property and more, so Tom quotes them one on one rather than on the website. Send him a message or a text and he'll get back to you with real numbers for your situation.
How mortgage rates workRate locks explained
Whether a refinance makes sense depends on your current loan, your goals and the costs involved. Tom's free mortgage checkup looks at your loan and tells you plainly if a change is worth it, with nothing expected.
Free mortgage checkupWhen to refinanceRefinance options
New Hampshire Housing has down payment and closing cost assistance programs for buyers who qualify, and gift funds from family can help too. Tom can tell you which ones may fit you.
NH down payment assistanceUsing gift funds
Elite Mortgage Group is a broker with access to 45 lenders, including options for self-employed borrowers and real estate investors, like bank statement and rental income loans.
Self-employed mortgagesBank statement loansInvestor loans
New Hampshire has no income tax on wages, but property taxes vary a lot from town to town, so it helps to compare a few towns before you choose. Tom lives in Litchfield and works with buyers across southern NH.